

Mehr zum Buch
This text prepares first-year graduate students and advanced undergraduates for empirical research in economics, equipping them for specialization in econometric theory, business, and sociology. Derived from a course taught by Arthur S. Goldberger at the University of Wisconsin–Madison and Stanford University, it is designed for two semesters and provides a thorough grounding in introductory statistical inference along with substantial interpretive material. The text balances rigor and intuition, encouraging students to form their own critical opinions. It covers fundamentals such as classical regression and simultaneous equations, and offers clear explorations of asymptotic theory and nonlinear regression. To accommodate varying levels of preparation, it begins with a comprehensive review of statistical concepts and methods before progressing to the regression model and its variants. Bold subheadings introduce key concepts throughout each chapter, which conclude with exercises designed to reinforce and extend the material. Many exercises involve real microdata analyses and are well-suited for homework and test questions, ensuring that students can apply what they have learned effectively.
Buchkauf
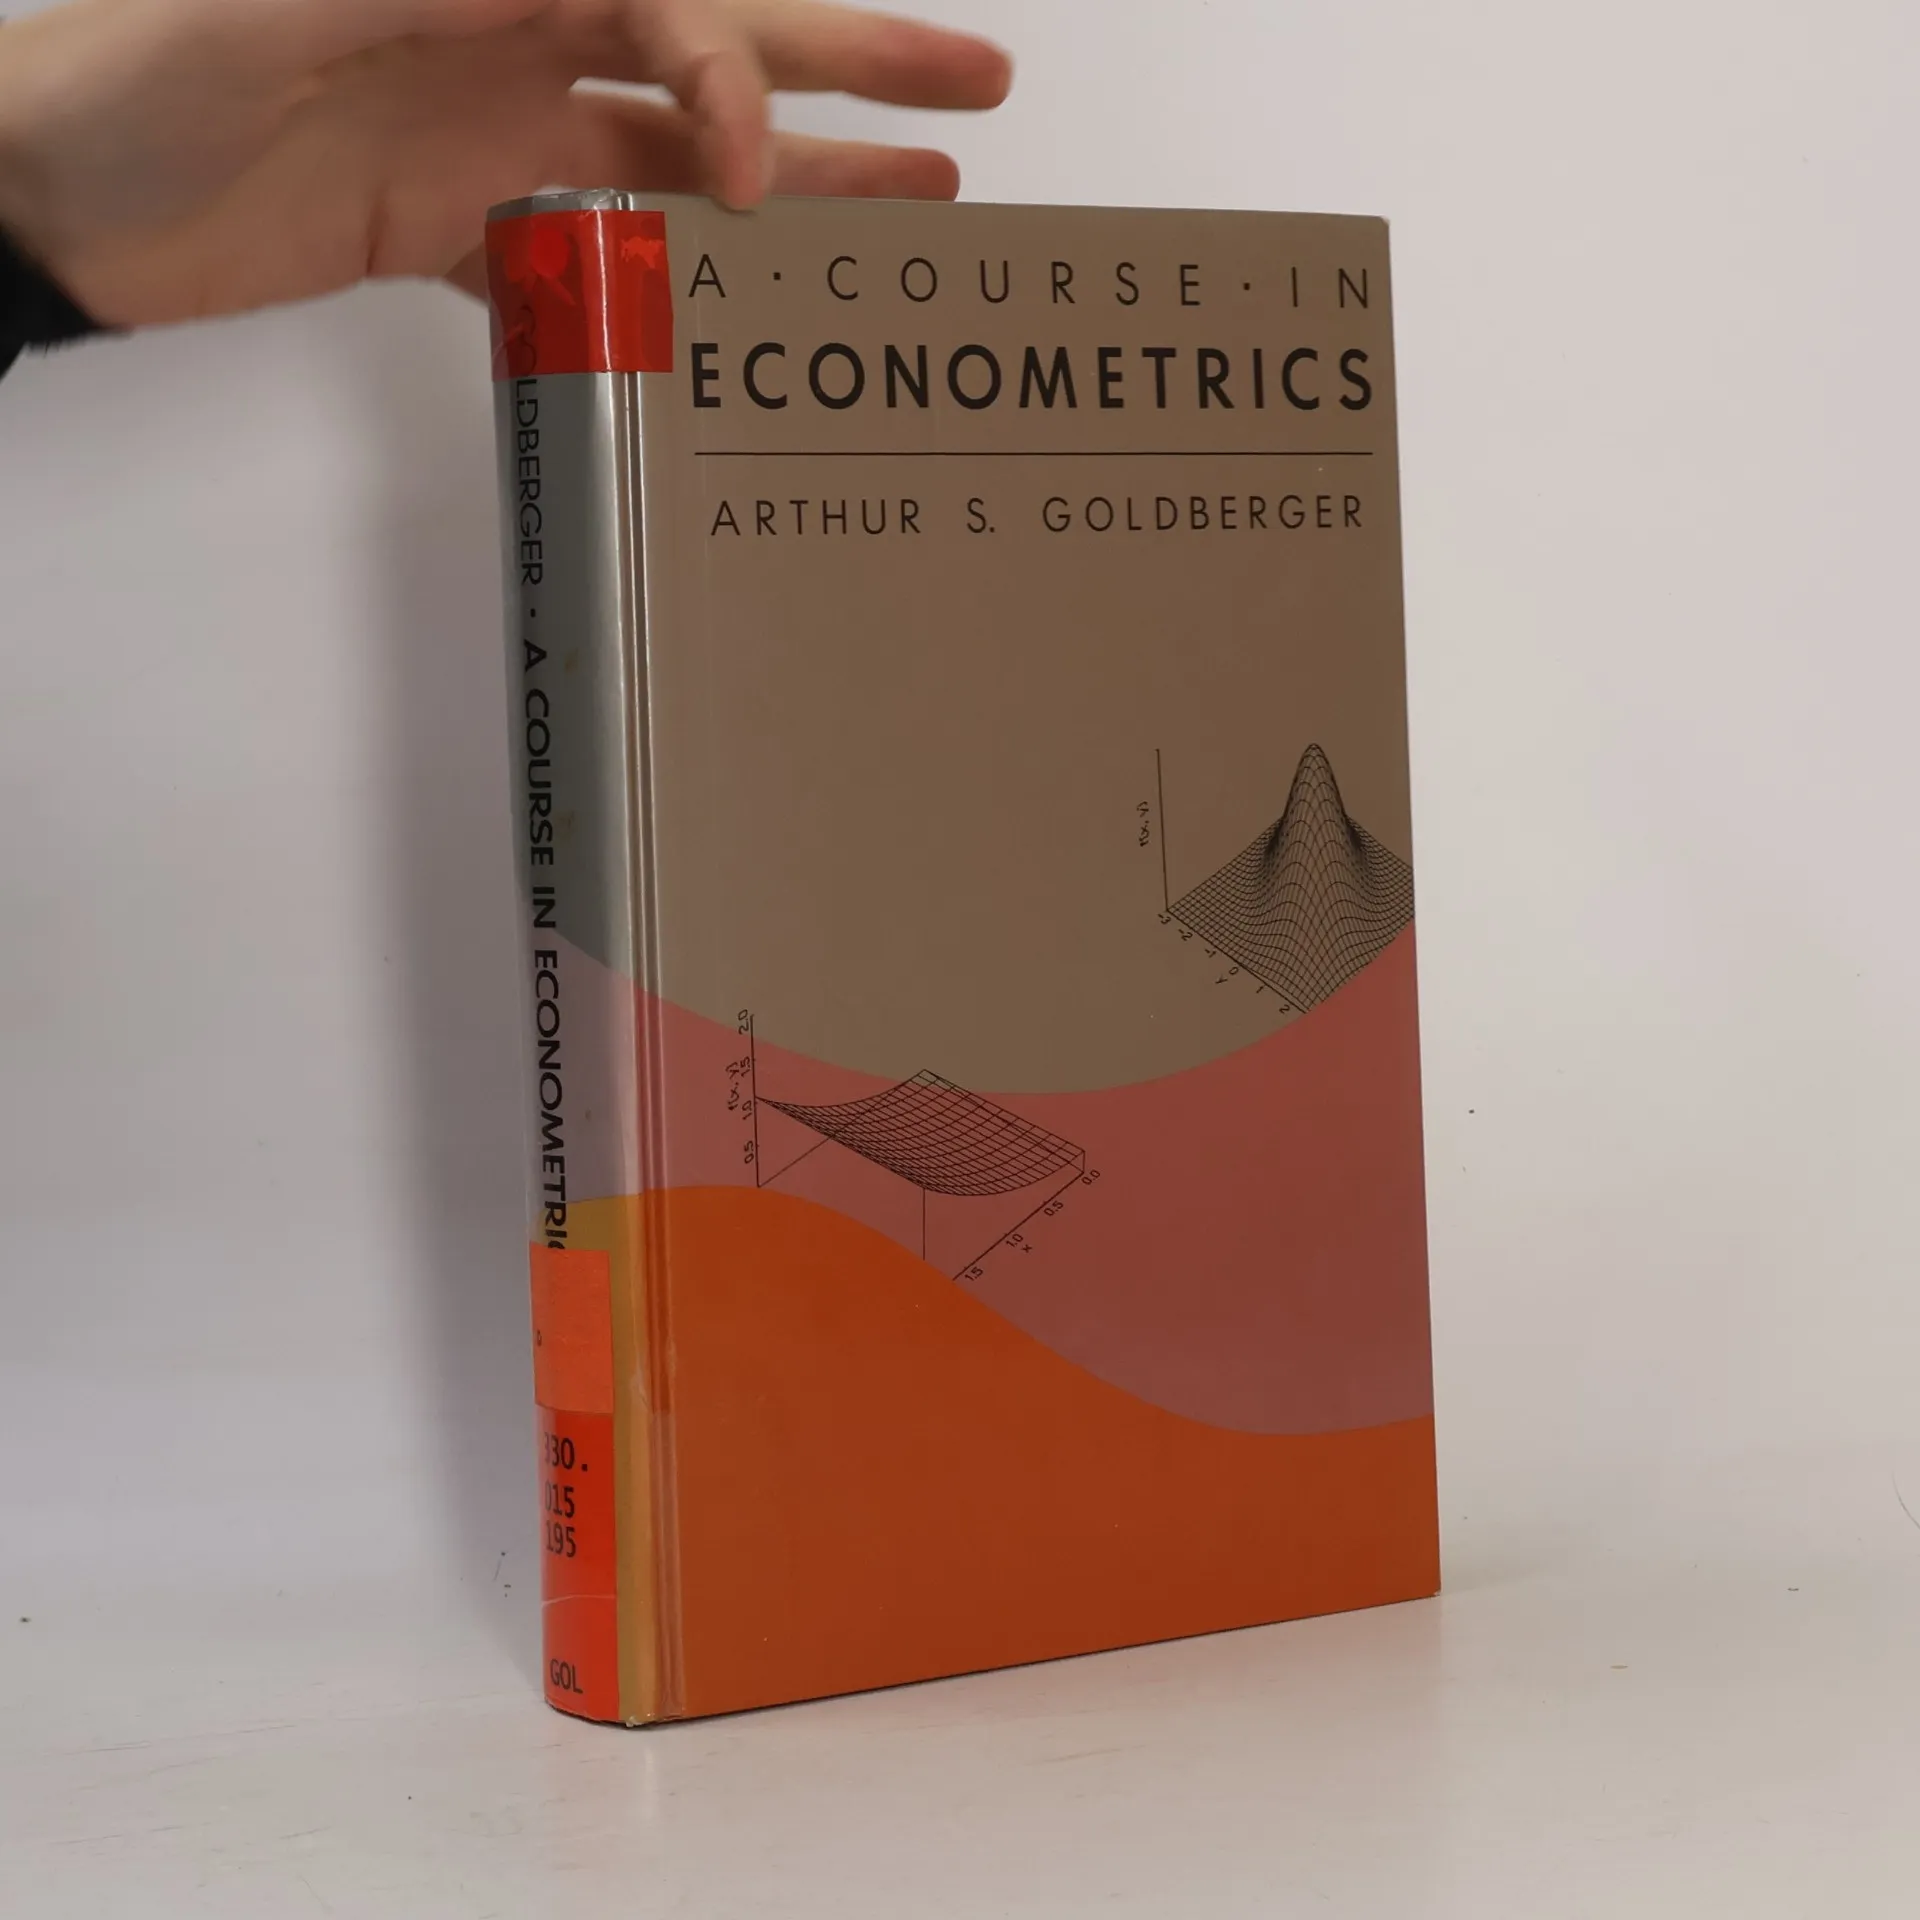
A Course in Econometrics, Arthur S. Goldberger
- Sprache

- Erscheinungsdatum
- 1991
- Einband
- (Hardcover),
- Buchzustand
- Gebraucht - Sehr gut
- Preis
- 12,89 €inkl. MwSt.
Keiner hat bisher bewertet.
- Titel
- A Course in Econometrics
- Sprache
- Englisch
- Autor*innen
- Arthur S. Goldberger
- Verlag
- Harvard University Press
- Erscheinungsdatum
- 1991
- Einband
- Hardcover
- Seitenzahl
- 432
- ISBN10
- 0674175441
- ISBN13
- 9780674175440
- Reihe
- Schlagwörter
- Handel, Wissenschaft, USA
- Beschreibung
- This text prepares first-year graduate students and advanced undergraduates for empirical research in economics, equipping them for specialization in econometric theory, business, and sociology. Derived from a course taught by Arthur S. Goldberger at the University of Wisconsin–Madison and Stanford University, it is designed for two semesters and provides a thorough grounding in introductory statistical inference along with substantial interpretive material. The text balances rigor and intuition, encouraging students to form their own critical opinions. It covers fundamentals such as classical regression and simultaneous equations, and offers clear explorations of asymptotic theory and nonlinear regression. To accommodate varying levels of preparation, it begins with a comprehensive review of statistical concepts and methods before progressing to the regression model and its variants. Bold subheadings introduce key concepts throughout each chapter, which conclude with exercises designed to reinforce and extend the material. Many exercises involve real microdata analyses and are well-suited for homework and test questions, ensuring that students can apply what they have learned effectively.